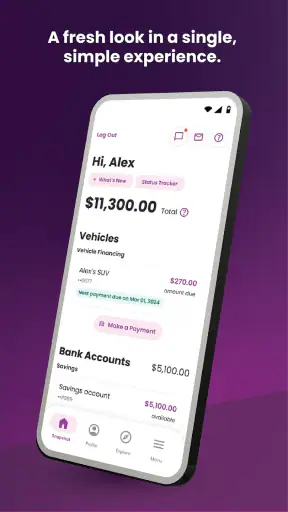
I spent time with Ally: Bank, Auto & Invest as a finance app, and my first impression is that it tries to bring several money tasks into one place rather than acting as a narrow banking tool. That matters if you already use Ally Financial and want a single mobile starting point for everyday banking, car-finance activity, and investing. It is free to download, rated for Everyone, and its broad purpose is reflected in the store summary: it is designed for “all things finance.”
That broad promise is also the main question to ask before installing it: do you want one app connected to Ally, or are you looking for a bank-neutral budgeting tool, a dedicated investing platform, or a simple account viewer? In my experience, the app makes the most sense for an existing Ally customer who values convenience across related financial services. It is less compelling for someone who wants to compare many banks, manage accounts from different institutions, or keep investing completely separate from daily banking.
How the app fits into everyday money management
The application comes from Ally Financial, so its identity is different from that of an independent budgeting app. Rather than building a financial picture by pulling together accounts from many providers, it is centered on Ally’s own services. That can make the experience feel more coherent when your checking, savings, vehicle financing, or investment relationship is already with the same company.
I would describe it as a central control point rather than a full financial coach. A control point helps you check what is happening, move through the services you use, and reduce the need to switch between separate mobile products. A coach would go further by helping you plan, interpret spending, or make decisions across your entire financial life. Those are not the same job, and expecting the app to replace every specialist tool can lead to disappointment.
The product has been available since April 2012, which gives it a long presence in mobile finance. Its current version is 26.14.0, and it requires at least iOS 10. That compatibility requirement is relatively approachable for many users, although anyone relying on an older device should check the operating system before making it part of a daily routine.
Its public audience is substantial: the app has more than a million installs, an average rating of 4.4, and roughly forty-one thousand ratings. Those figures suggest that it has reached well beyond a small group of early adopters. They do not guarantee that every banking workflow will suit every person, but they do make it easier to view the app as an established option rather than an experiment.
What “free” means when choosing it
The app itself is free, so there is no purchase price to weigh against its convenience. That is useful for anyone who wants to try the mobile experience without paying for access first. Still, free access should not be confused with a promise that every financial product or service available through a bank is cost-free. The app is a gateway to Ally Financial services, and the value of those services depends on the account or product you choose.
I would therefore separate two decisions. The first is whether the application is worth installing, and the answer is easy to test because the download costs nothing. The second is whether Ally’s banking, auto, or investment products suit your needs. That second decision deserves its own review of terms and suitability; the app alone cannot make an expensive or unsuitable financial product a good choice.
This distinction is important when comparing it with paid personal-finance software. A subscription budgeting app may charge for detailed planning tools, but it may also be designed to work across several financial institutions. Ally offers a different kind of value: no app purchase price and a direct relationship with one financial provider. If you want broad account aggregation, paying for a specialist may be more useful than choosing a free bank-specific app.
The practical value of one financial home
The strongest benefit is reduced friction. When a person uses more than one Ally service, opening one application to check different parts of that relationship is simpler than remembering separate tools. I find that especially useful during short moments: checking whether a payment has cleared, looking at a balance before moving money, or reviewing an investment account without leaving the same mobile environment.
A realistic example is a weekday morning before a large bill is due. I might open the app to see whether the money needed for that payment is in the right place, then review the relevant account rather than relying on memory. If I also have an Ally auto-finance relationship or investment account, the same session can provide a broader view of what needs attention. The benefit is not dramatic automation; it is the small reduction in mental and app-switching overhead that makes routine checking easier.
Another useful habit is using the app as a quick checkpoint rather than waiting for a monthly statement. Short, regular checks can help catch an unfamiliar transaction or an account balance that is lower than expected. That does not replace careful reconciliation, but it can make financial awareness more immediate. For me, this is a better use of a mobile banking app than opening it repeatedly without a specific question in mind.
The combined finance focus may also help households that divide responsibilities. One person can use the app to check banking activity while another reviews a vehicle-finance or investing relationship, provided the account access and security arrangements are appropriate. The convenience comes from having related services presented through the same financial institution, not from the app becoming a shared household budget planner.
Where the experience may feel limited
The same focus that makes the app convenient can make it restrictive. If your financial life is spread across several banks, credit unions, brokerages, and lenders, this is unlikely to become a complete dashboard. You may still need another app or a spreadsheet to see the full picture. A bank-specific application can be excellent at showing its own relationship while offering little help with accounts held elsewhere.
I would also avoid treating the app as a substitute for investment research or financial advice. The presence of an investing area does not automatically make it the best place to learn about markets, compare providers, or build a detailed long-term plan. Someone who wants extensive analytical tools may prefer a dedicated investment platform. Someone who mainly wants spending categories and household targets may prefer a budgeting application built around those tasks.
There is also a psychological trade-off in combining banking, auto finance, and investing. Seeing everything together can improve awareness, but it can also encourage quick decisions based on a snapshot. A lower cash balance beside a long-term investment balance does not mean the investment should be touched, and a convenient mobile interface should not replace a considered plan. I recommend using the app to observe and organize, then slowing down when a decision affects debt, savings, or investments.
Security habits remain part of the experience, even when the application itself is easy to use. I would protect the device, use the strongest available sign-in method, avoid checking sensitive information on an untrusted connection, and review activity instead of assuming that a familiar-looking notification is genuine. These are not reasons to avoid mobile banking; they are the practical responsibilities that come with putting financial access in your pocket.
Small workflows that make it more useful
One of my preferred approaches is to give each visit a purpose. Before opening the app, I decide whether I am checking available money, reviewing recent activity, looking at an auto-finance obligation, or checking an investment position. That simple habit prevents the application from becoming a source of vague financial anxiety and turns it into a short verification tool.
A second approach is to check before acting, not after. If I am about to move money or make a large purchase, I first look at the relevant balance and recent activity. This is more reliable than estimating from a previous memory. It also helps separate money that is genuinely available from money already committed to a pending obligation.
A third trade-off concerns consolidation. Keeping related services in one app can make routine monitoring easier, but I would not consolidate purely for convenience. I would compare the underlying products on their own terms and then decide whether the mobile experience adds enough value. The free download is a low-risk way to test the interface, but it should not be the reason to open an account or move an investment.
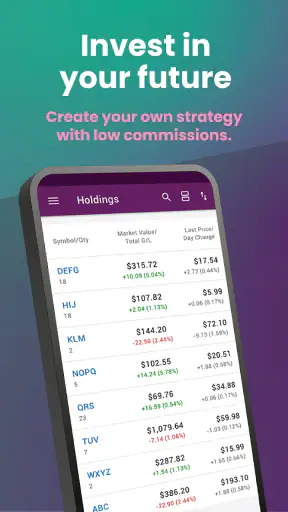
For investment users, I would use the app for periodic awareness rather than constant checking. Frequent price watching can create noise and encourage emotional reactions, while occasional reviews can support a longer-term plan. The app’s convenience makes access easy; that is helpful when used deliberately and unhelpful when it turns every market movement into an invitation to act.
Who is most likely to appreciate it?
I think the clearest audience is an existing or prospective Ally customer who wants mobile access to several Ally Financial relationships. The app is especially sensible if your priority is convenience, quick account visibility, and fewer separate finance apps. Its free price also makes it straightforward to try before deciding how central it should become in your routine.
It may also suit someone who is comfortable managing money independently and mainly needs a reliable place to check activity. If you already know which accounts you use and do not need extensive coaching, a focused provider app can be less distracting than a feature-heavy financial planner. The large install base and strong average rating make it a reasonable candidate for that role, while still leaving room for individual experiences to differ.
I would be more cautious if your main goal is a complete household budget. In that situation, an app designed to combine accounts from multiple institutions, categorize spending, and set detailed goals may be a better companion. Likewise, a serious investor who needs advanced research or specialized portfolio analysis should look at dedicated investment software rather than assuming that a combined finance app will cover every requirement.
It is also not the obvious choice for someone who wants a neutral comparison of financial products. Because the experience is tied to Ally Financial, it naturally makes the most sense within that ecosystem. A person who changes providers often, manages many outside accounts, or wants a single view across unrelated institutions may find that the convenience fades quickly.
My buying decision: try the app, judge the relationship separately
My verdict is positive, with a clear boundary. Ally: Bank, Auto & Invest is worth trying when you already use Ally Financial and want one free mobile entry point for related financial services. The established history, broad adoption, and 4.4 average rating support confidence that it is a serious everyday option, while the Everyone age rating keeps its intended audience broad.
I would not choose it solely because it is free, and I would not treat the download as evidence that Ally’s underlying products are automatically the best fit. The application delivers convenience, but convenience has the greatest value when the financial relationship behind it already matches your needs. If you want a provider-centered mobile experience, it can simplify routine checks. If you want an institution-neutral financial command center, a specialist alternative will probably serve you better.
In short, I see it as a practical tool for monitoring and managing an Ally relationship, not as a universal replacement for budgeting software, investment research platforms, or careful financial planning. Install it if consolidation and quick access are what you need. Skip it if your priority is broad multi-provider control or deep specialist features. That distinction makes the free trial meaningful: test whether it reduces effort in your actual money routine, then make the larger financial decision on the products themselves.


